
 Post
 Share
 Share
 Post
 Pin
 Send
 Send
Over the past few years, many online banks have built reputations for offering competitive financial products. Tangerine and EQ Bank are no exception. In fact, if you decide to constantly hunt down the most competitive rates for every single financial product, chances are that you will eventually sign up for both banks.
That being said, many people prefer to keep their finances simple. Since Tangerine and EQ both have a variety of competitive offerings, it may be easier to sign up for one bank and stick with them for most financial products. Although you will miss out on other institutions’ perks, you will also save a lot of time and energy.
If you do wish to stick to one bank, it is important to select one whose products cater to your needs. To help you narrow down the choices, we will be comparing EQ Bank and Tangerine’s financial products, category by category. Before going into the specifics, let’s dive in this EQ Bank vs Tangerine comparison table, that covers the highlights of each bank’s main financial products.
EQ Bank vs Tangerine
| EQ Bank | Tangerine | |
| Chequing Account | – Personal Account combines everyday banking and savings features – 1.00% base interest rate, or 2.75% with qualifying recurring direct deposits of at least $2,000 per month – No monthly fees – Must be the age of majority to register | – 0.01-0.10% interest rate – Free ATM withdrawal at Scotiabank/Global Alliance, $1.50/withdrawal for other Canadian ATMs, $3/withdrawal everywhere else – Must be 16+ to register – Can request 50 free cheques |
| Savings Account | – 2.35% with a 10-day Notice Savings Account or 2.75% with a 30-day Notice Savings Account – 2.50% for USD accounts – No monthly fees or minimum balance – Must be the age of majority to register | – 0.30% regular interest rate for CAD accounts; new clients can currently earn 4.50% for up to 5 months (0.10% for USD accounts) – Automated savings goals – Must be 16+ to register |
| Payment Cards | – Customers can order a reloadable prepaid Mastercard linked to their Personal Account – 0.5% cash back on purchases – Earns the same interest rate as the linked Personal Account | – Bank account comes with Visa Debit card – Can apply for credit cards |
| Investments | – Supports RSP, TFSA, FHSA, and non-registered accounts – Can purchase GICs with terms ranging from 3 months to 10 years | – Supports registered and non-registered investment accounts – Offers GICs with terms from 3 months to 5 years and mutual fund portfolios with MERs ranging from approximately 0.76% to 1.06% |
| Sending and Receiving Money | – Supports Interac e-Transfer, EFT, and digital bill payments – Can load up to $10,000 per day onto the EQ Bank Card and spend up to $10,000 per day – $500 daily ATM withdrawal limit | – Supports Interac e-Transfer, EFT, and digital bill payments – Can spend up to $2,500/day – $1,200/day ATM withdrawal limit |
| Mobile App | – View balances and transaction history – Deposit cheques – Pay bills, use EFT | – View balances and transaction history – Deposit cheques – Pay bills, use EFT – Budget tools – Savings goal tracking – Create automated transfer rules |
EQ Bank vs Tangerine: Chequing Accounts
The humble chequing account is a staple financial product. It is also one of the more difficult categories to compare EQ Bank and Tangerine across. Tangerine offers its No-Fee Daily Chequing Account, a traditional Canadian-dollar chequing account. EQ Bank, meanwhile, offers its Personal Account, which combines many of the features of a chequing account with the ability to earn interest. EQ clients can also transfer money from their Personal Account to the EQ Bank Card, a prepaid reloadable Mastercard.
Review of perks
Both Tangerine’s No-Fee Daily Chequing Account and EQ Bank’s Personal Account offer no monthly account fees and free Interac e-Transfers. However, EQ’s Personal Account currently pays a 1.00% base interest rate. Clients who set up and maintain qualifying recurring direct deposits of at least $2,000 per month can earn 2.75% interest on eligible Personal and Joint Accounts, as well as their EQ Bank Card balance.
EQ Bank also does not charge its own fees for Canadian ATM withdrawals. If a Canadian ATM provider charges a fee, EQ will reimburse up to $5 per withdrawal for up to five withdrawals per month. Tangerine offers free access to Scotiabank and Global ATM Alliance machines, while withdrawals from other ATMs cost $1.50 in Canada and $3 outside Canada.
The Personal Account does have a few limitations. Most notably, EQ Bank does not offer cheques or bank drafts through the account and does not provide in-branch service. Customers must also have reached the age of majority in their province or territory to open an EQ Bank account. Tangerine’s Chequing Account, by comparison, is available to Canadian residents aged 16 and older and includes a first book of 50 cheques at no charge.
Winner: EQ Bank
EQ Bank vs Tangerine: Savings Accounts
When it comes to savings, EQ Bank and Tangerine take different approaches. Tangerine’s Canadian-dollar Savings Account currently offers a standard interest rate of 0.30%. However, new Tangerine clients can currently earn a promotional rate of 4.50% for up to 5 months. Tangerine also offers tools that allow clients to automate transfers, create savings goals, and keep their everyday spending separate from their savings.
EQ Bank offers Notice Savings Accounts for clients willing to wait before accessing their money. The 10 Day Notice Savings Account currently pays 2.35%, while the 30 Day Notice Savings Account pays 2.75%. Neither account charges monthly fees or requires a minimum balance. However, these accounts are designed specifically for savings and do not support everyday banking transactions such as Interac e-Transfers, bill payments, or ATM withdrawals.
Both EQ Bank and Tangerine also offer U.S. dollar savings accounts. Tangerine’s US Dollar Savings Account currently pays 0.10% interest. In comparison, EQ Bank’s US Dollar Account currently pays 2.50% interest, with no monthly fees or minimum balance requirements. EQ also supports international money transfers through Wise. As a result, EQ Bank currently offers the stronger rate for U.S. dollar savings. Note that EQ Bank’s Notice Savings Accounts, US Dollar Account and International Money Transfers are not currently available to Quebec residents.
Winner: EQ Bank for ongoing rates; Tangerine for eligible new clients during the promotional period
EQ Bank vs Tangerine: Payment Cards
Both Tangerine and EQ Bank offer payment cards that allow customers to make purchases in-store and online. Tangerine provides its Client Card with the Chequing Account, while EQ Bank customers can order the EQ Bank Card separately. Tangerine also offers a number of credit cards, including the Money-Back Credit Card (heads up: Hardbacon readers currently qualify for a 10% cash back offer when signing up for a new Money-Back Credit Card). However, for the sake of keeping the comparison as fair as possible, we will only focus on the debit-like cards that are linked to customers’ bank accounts in this section.
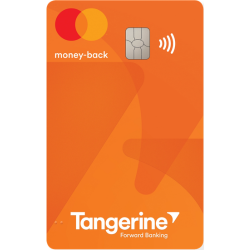
Tangerine’s Client Card is a straightforward debit card that allows you to make purchases via your bank account’s balance. It uses the Visa Debit network, so you can expect the card to work at any vendor that accepts Visa, regardless of whether you are in Canada or abroad.
EQ’s Bank Card is not actually a debit card, but a prepaid reloadable Mastercard. Users load money onto the card through their Personal Account before making purchases. They earn 0.5% cash back on purchases and interest on their card balance at the same rate as their linked Personal Account. The current base rate is 1.00%, while eligible customers with qualifying recurring direct deposits can earn 2.75%.
On paper, EQ’s Bank Card is more competitive than Tangerine’s Client Card. However, depending on your lifestyle, the Client Card may be a better pick. Establishments that do not accept credit cards may refuse the EQ Bank Card — and you will have to remember to reload the card when the balance gets low. EQ still wins this showdown section, but with an acknowledgement of its pitfalls.
Winner: EQ Bank
EQ Bank vs Tangerine: Investments
EQ currently offers four investment account types: Retirement Savings Plan accounts (RSPs), Tax-Free Savings Accounts (TFSAs), First Home Savings Accounts (FHSAs), and non-registered accounts. Since RSPs, TFSAs, and FHSAs are regulated by the government, each account type comes with its own benefits and requirements. At the moment, EQ does not offer tradable investment products such as index funds. However, it does offer Guaranteed Investment Certificates (GICs) with rates ranging from 2.35% to 4.25% and terms from 3 months to 10 years. Current featured rates include 3.70% for a non-registered 1-year GIC and 4.25% for a registered 5-year GIC.
Tangerine’s mutual fund portfolios fall into three main categories: Core, Global ETF, and Socially Responsible Global. Core Portfolios provide diversified exposure with a greater emphasis on Canadian investments and currently have an MER of 1.06%. Global ETF Portfolios invest through exchange-traded funds across international markets and have an MER of approximately 0.76%. Socially Responsible Global Portfolios focus on companies selected using environmental, social, and governance criteria and have an MER of approximately 0.82%. Within each category, investors can select a portfolio based on their investment goals and risk tolerance.
Winner: Tangerine
Since EQ Bank and Tangerine offer such radically different investment products, it is tough to declare a winner for the investment category. Ultimately, we selected Tangerine as the winner (largely because they offer a wider variety of investment products). Still, many people will find that EQ’s investment accounts are a better fit for their specific financial situation. We highly recommend reviewing your investment goals before opening up an account with either bank.
EQ Bank vs Tangerine: Sending and Receiving Money
Both EQ and Tangerine make it easy to deposit and access money. Clients at either bank may move their money around via Interac e-Transfer or an Electronic Funds Transfer (EFT). Both banks also support mobile cheque deposits and online bill payments. They also have similar withdrawal options, though daily limits and ATM policies vary.
Tangerine clients may spend up to $2,500 on their debit card each day. They may also withdraw up to $1,200 from an ATM. This daily ATM limit cannot be changed online, although clients can contact Tangerine to request a change. Tangerine charges $1.50 for withdrawals from other ATMs in Canada and $3 for withdrawals from machines outside Canada that are not part of the Global ATM Alliance.
EQ clients may load up to $10,000 onto their EQ Bank Card per day and can spend up to $10,000 per day, with a maximum ATM withdrawal limit of $500 per day. EQ Bank does not charge a fee for Canadian ATM withdrawals. If an ATM provider charges its own fee, EQ will reimburse up to $5 per withdrawal for up to five withdrawals per month. Overall, both EQ and Tangerine make it easy to move money around, but EQ’s ATM reimbursement policy gives it an advantage for clients who regularly use different Canadian ATMs.
Winner: EQ Bank
EQ Bank vs Tangerine: Mobile App
The quality of your bank’s mobile app can cause (or prevent) a lot of headaches. Fortunately, EQ and Tangerine clients have access to relatively useful mobile apps. Both apps allow you to view your balances and transaction history, deposit cheques, pay bills, and transfer money between different linked bank accounts.
Still, Tangerine’s app is packed with more features. Most notably, the app allows you to set up and monitor a budget. You can also create and track savings goals, locate partnered ATMs near you, and set automated transfer rules. Plus, the app is responsive and has an intuitive layout, ultimately leading to a stress-free experience for users.
Winner: Tangerine
EQ Bank vs Tangerine: Which Bank is Best Overall?
If you tally up the results of each section, you might have noticed that it’s a tight race, with EQ Bank winning three categories, Tangerine winning two, and the savings category depending on whether you prioritize ongoing rates or Tangerine’s promotional offer. At the end of the day, EQ Bank’s perks are a bit more appealing than Tangerine’s, making it the winner of our banking showdown. Still, as we have already mentioned, each bank’s products come with their own pros and cons. We recommend keeping your own lifestyle and habits in mind before opening an account.


